

Class 12 Accountancy Practice Assignments: CBSE Class 12 Accountancy Analysis of Financial Statements Assignment
Access comprehensive school assignments for Part 2 Chapter 04 Analysis Of Financial Statements using the CBSE Class 12 Accountancy Analysis of Financial Statements Assignment. Designed to align with the 2026-27 CBSE academic guidelines, these practice sets help Class 12 Accountancy students reinforce core concepts and improve their problem-solving accuracy.
Download Part 2 Chapter 04 Analysis Of Financial Statements Assignment PDF with Solutions
Access the complete assignment PDF for Class 12 Accountancy below. Regular practice with these targeted academic tasks builds familiarity with standard question patterns and helps secure higher marks in final school evaluations.
Important Questions for NCERT Class 11 Accountancy Financial Statements
Question . Rent paid on 1st October, 2020 for one year upto 30th September, 2020 was Rs.2,400. Rent paid on 1st October, 2020 for the year upto 30th September, 2020 was Rs.3,200. Rent shown in the Profit and Loss Account for the year ended on 31st December, 2020, would be :
(a) Rs.6,000
(b) Rs.3,200
(c) Rs.3,000
(d) Rs.2,600
Answer : D
Question . Accrued income is :
(a) A Liability
(b) Revenue
(c) An Asset
(d) An Expense
Answer : C
Question Revenue Income is transferred to
(a) Profit and Loss Account.
(b) Trading and Profit and Loss Account.
(c) Balance Sheet.
(d) Miscellaneous Income.
Answer : B
Question Capital Expenditure is included in
(a) Trading Account.
(b) Profit and Loss Account.
(c) Balance Sheet.
(d) Profit and Loss Appropriation Account.
Answer : C
Question . A new firm commenced business on 1st January, 2020 and purchased goods costing Rs.90,000 during the year. A sum of Rs.6,000 was spent on freight inward. At the end of the year the cost of goods still unsold was Rs. 15,000 (Realisable Value 12,000). Sales during the year was Rs. 1,20,000. What is the gross profit earned by the firm?
(a) Rs.42,000
(b) Rs.30,000
(c) Rs.36,000
(d) Rs.39,000
Answer : A
Question . Income tax paid by a sole trader is reflected in his financial statements :
(a) On the debit side of the Trading Account
(b) On the debit side of the Profit and Loss Account
(c) As an asset in the Balance Sheet
(d) As way of deduction from capital in the Balance Sheet
Answer : D
Question . Which of the following statements is correct:
(a) King’s International — P & L A/c as on 31st March, 2020
(b) King’s International — P & L A/c for the year ended 31st March 2020
(c) King’s International — P & L A/c for the year ended 31st March, 2020
(d) King’s International — P & L A/c for the current year (2019-2020)
Answer : C
Question . If closing stock appears in Trial Balance then it will be appearing in ;
(d) Trading Account
(b) Balance Sheet
(c) Profit & Loss Account
(d) Trading A/c & Balance Sheet
Answer : B
Question Capital Receipts are shown in
(a) Balance Sheet.
(b) Trading Account.
(c) Trading Account.
(d) Capital Account.
Answer : A
Question . The purpose of preparing final accounts is to ascertain :
(A) Profit or loss
(B) Capital
(C) The value of assets
(D) Profit or loss and financial position
Answer : D
Question Closing Stock is valued at Cost or Net Realisable Value (Market Value), whichever is less because of
(a) Going Concern Concept.
(b) Accrual Concept.
(c) Prudence Concept.
(d) Consistency Concept.
Answer : C
Question Loss on sale of an old car is debited to
(a) Profit and Loss A/c.
(b) Car A/c.
(c) Depreciation A/c.
(d) Trading Account.
Answer : A
Question Closing Stock, if given outside the Trial Balance, is shown in
(a) Trading Account and Balance Sheet.
(b) Profit and Loss Account.
(c) Profit and Loss Account and Balance Sheet.
(d) Balance Sheet.
Answer : A
Question Sales are equal to
(a) Cost of Goods Sold + Gross Profit.
(b) Cost of Goods Sold — Gross Profit,
(c) Gross Profit — Cost of Goods Sold.
(d) Purchases + Gross Profit.
Answer : A
Question Income tax paid by a sole trader is shown
(a) on the debit side of the Trading Account.
(b) on the debit side of the Profit and Loss Account.
(c) as deduction from capital in the Balance Sheet.
(d) as addition to capital in the Balance Sheet.
Answer : C
More Important Questions for NCERT Class 11 Accountancy Financial Statements
Question. List any two information required to be given in the balance sheet of a company or by way of foot Notes.
Answer : (i) Uncalled Liability on share partly paid up .
(ii) Arrears of fixed Cumulative Dividend.
Question. Name two tools of Financial Analysis ?
Answer : (i) Comparative Financial Statements.
(ii) Ratio Analysis etc.
Question. Give the heading under which the following items will be shown in a company’s Balance sheet:
(i) Goodwill.
(ii) Preliminary Expenses
(iii) Loose Tools
(iv) Capital Redemption Resave.
(v) Live Stock.
Answer : (i) Fixed Assets.
(ii) Miscellaneous Expenditures
(iii)Current Assets Loans & Advance under Current Assets.
(iv)Reserve and Surplus.
(v)Fixed Assets.
Question. Give two example each of Non-Current Assets and Non- Current Liabilities.
Answer : Non-Current Assets – Building, Machinery.
Non-Current Liabilities – Share Capital , Debentures.
Question. Give the format of the Balance sheet of a company(main headings only) as per the requirement of Schedule VI of the companies Act.1956.
Answer : Balance sheet as on______
Liabilities Rs. Assets Rs.
Share capital Fixed Assets
Reserve & surplus Investment
Secured Loans Current Assets,
Unsecured Loans Loan and Advances
(a) Current Assets
(b) Loans & Advance
Current Liabilities & Provision Miscellaneous Expenditures
(a) Current Liabilities Profit & Loss amount (Dr.Balance)
(b) Provision
Question. What is Vertical Analysis?
Answer : The Analysis which is made to review the financial statements of one particular year only is called Vertical Analysis.
Question. Prepare Comparative income statement from the following information for the years ended march
31,2003 and 2004.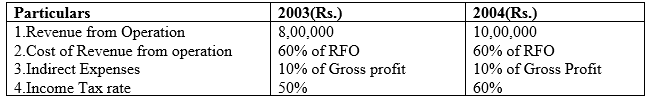
Answer : Percentage Change –
Net sale 25%
Cost of Goods sold 25%
Gross profit 25%
Indirect Expenses 87.50%
Net profit before Tax 18.05%
Income Tax 41.67%
Net Profit after Tax 5.56%
Question. List any three items that can be shown as contingent Liabilities in a company’s Balance sheet.
Answer : (i) Claims against the Company not acknowledged as debts .
(ii) Uncalled Liability on partly paid shares.
(iii)Arrears of Dividend on Cumulative preference shares.
Question. State whether the Balance sheet of a Company is prepared ’ as on a particular date ‘ or ‘ as at a Particular date ‘ ?
Answer : Balance of a Company is prepared ‘ as at a particular date ‘.
Question. State any two items which are shown under the head ‘Investment’ in a company balance sheet.
Answer : (i) Government Securities.
(ii) Sinking Fund Investment.
Question. What is the interest of Shareholders in the analysis of Financial statements?
Answer : (i) They want to judge the present and future earning capacity of the business.
(ii) They want to judge the safety of their investment.
Question. Which item is assumed to be 100 in the case of common size Income statement .
Answer : Sales.
Question. Give the example of Vertical Analysis?
Answer : Ratio Analysis.
Question. The following balance have been from the book of Sahara Ltd. Share capital Rs.10,00,000, securities Premium Rs. 1,00,000, 9% Debentures Rs. 500,000, Creditors Rs. 200,000., Proposed Dividend Rs. 50,000. , Freehold property RS. 9,00,000, share of Reliance Industries Rs. 4,00,000, Work-in- Progress Rs. 4,00,000, Discount on Issue of Debentures Rs. 1,00,000. Prepare the balance sheet of the company as per schedule VI part 1 of the companies Act.1956.
Answer : Total of Balance Sheet Rs.18,50,000.
Question. What is Horizontal Analysis?
Answer : The analysis which is made to review and compare the financial statements of two or more then two Years is called Horizontal Analysis.
Question. How will you show the following items in the Balance sheet of a company.
(i) Calls in Arrears
(ii) Calls in Advance.
Answer : (i) Calls in Arrears: It is deducted from the subscribed capital.
(iii) Calls in Advance: It is shown separately under the subscribed capital.
Question. Under what heads the following items on the Liabilities side of the Balance sheet Of a company will be presented
(i) Proposed Dividend.
(ii) Unclaimed Dividend.
Answer : Items Heading Sub-Heading
Proposed dividend Current Liabilities Provision
& Provision
Unclaimed dividend Current Liabilities Current Liabilities
& Provision
Question. Give the example of Horizontal Analysis.
Answer : Comparative Financial Statement.
Question. How is a Company’s balance sheet different from that of a Partnership firm? Give Two point only.
Answer : (i) For company’s Balance Sheet there are two standard forms prescribed under the companies Act.1956 Whereas there is no standard form prescribed under the Indian partnership Act,1932 for a partnership Firms balance sheet.
(ii) In case of a company’s Balance sheet previous years figures are required to be given whereas it is not so in the case of a partnership firms balance sheet.
Question. How is analysis of Financial statements suffered from the limitation of window dressing ?
Answer : Analysis of financial statements is affected from the limitation of window dressing as companies hide Some vital information or show items at incorrect value to portray better profitability and financial Position of the business, for example the company may overvalue closing stock to show higher profits.
Question. Interpretation of Financial Statements includes:
(a) Criticisms and Analysis
(b) Comparison and Trend Study
(c) Drawing Conclusion
(d) All the above
Answer: (d) All the above
Question. Horizontal Analysis is also known as :
(a) Dynamic Analysis
(b) Structural Analysis
(c) Static Analysis
(d) None of these
Answer: (a) Dynamic Analysis
Question. Vertical Analysis is also known as :
(a) Static Analysis
(b) Dynamic Analysis
(c) Structural Analysis
(d) None of these
Answer: (a) Static Analysis
Question. Comparative Statements are also known as :
(a) Dynamic Analysis
(b) Horizontal Analysis
(c) Vertical Analysis
(d) External Analysis
Answer: (b) Horizontal Analysis
Question. Common-size Statement are also known as:
(a) Dynamic Analysis
(b) Horizontal Analysis
(c) Vertical Analysis
(d) External Analysis
Answer: (c) Vertical Analysis
Question. The most commonly used tools for financial analysis are:
(a) Comparative Statements
(b) Common-size Statement
(c) Accounting Ratios
(d) All the above
Answer: (d) All the above
Question. The analysis of financial statement by a shareholder is an example of:
(a) External Analysis
(b) Internal Analysis
(c) Vertical Analysis
(d) Horizontal Analysis
Answer: (a) External Analysis
Question. For calculating trend percentages any year is selected as:
(a) Current year
(b) Previous year
(c) Base year
(d) None of these
Answer: (c) Base year
Question. Tools for comparison of financial statements are :
(a) Comparative Balance Sheet
(b) Comparative Income Statement
(c) Common-size Statement
(d) All the above
Answer: (d) All the above
Question. Trend ratios and trend percentage are used in :
(a) Dynamic analysis
(b) Static analysis
(c) Horizontal analysis
(d) Vertical Analysis
Answer: (c) Horizontal analysis
Question. Comparative Financial Statements show:
(a) Financial position of a concern
(b) Earning capacity of a concern
(c) Both of them
(d) None of these
Answer: (c) Both of them
Question. Comparative financial analysis process shows the comparison between the items of which statement:
(a) Balance Sheet
(b) Profit & Loss Statement
(c) (a) and (b) both
(d) None of these
Answer: (c) (a) and (b) both
Question. Which of these are not the method of financial statement analysis ?
(a) Ratio Analysis
(b) Comparative Analysis
(c) Trend Analysis
(d) Capitalisation Method
Answer: (d) Capitalisation Method
Question. Common-size financial statements are mostly prepared:
(a) In proportion
(b) In percentage
(c) (a) and (b) both
(d) None of these
Answer: (b) In percentage
Question. Tangible assets of company increased from \( Rs 4,00,000 \) to \( Rs 5,00,000 \). What is the percentage of change ?
(a) 20%
(b) 25%
(c) 33%
(d) 50%
Answer: (b) 25%
Question. A company’s shareholders fund was \( Rs 8,00,000 \) in the year 2015. It because \( Rs 12,00,000 \) in the year 2016. What is percentage of change ?
(a) 100%
(b) 25%
(c) 50%
(d) 33.3%
Answer: (c) 50%
Question. A company’s net sales are \( Rs 15,00,000 \); cost of sales is \( Rs 10,00,000 \) and indirect expenses are \( Rs 3,00,000 \), the amount gross profit will be:
(a) \( Rs 13,00,000 \)
(b) \( Rs 5,00,000 \)
(c) \( Rs 2,00,000 \)
(d) \( Rs 12,00,000 \)
Answer: (c) \( Rs 2,00,000 \)
Question. Sales less Cost of goods sold is called :
(a) Operating Profit
(b) Gross Profit
(c) Net Profit
(d) Total Profit
Answer: (b) Gross Profit
Question. If total assets of a firm are \( Rs 12,00,000 \) and its non of non-current assets to total assets ?
(a) 50%
(b) 75%
(c) 25%
(d) 80%
Answer: (b) 75%
Question. If total assets of a firm are \( Rs 10,00,000 \) and its non-current assets are \( Rs 6,00,000 \), what will be the percentage of current assets on total assets ?
(a) 60%
(b) 50%
(c) 40%
(d) 30%
Answer: (c) 40%
Question. In a common-size Balance Sheet, total equity and liabilities are assumed to be equal to :
(a) 1,000
(b) 100
(c) 10
(d) 1
Answer: (b) 100
Question. Break-even point refers to that point where :
(a) Total Costs are more than Total Sales
(b) Total Costs are less than Total Sales
(c) Total Costs are half of the Total Sales
(d) Total Cost are equal to total sales
Answer: (d) Total Cost are equal to total sales
Question. Payment of Income Tax is considered as :
(a) Direct Expenses
(b) Indirect Expenses
(c) Operating Expenses
(d) None of these
Answer: (b) Indirect Expenses
Question. Vertical Analysis is also known as :
(a) Fluctuation Analysis
(b) Static Analysis
(c) Horizontal Analysis
(d) None of these
Answer: (b) Static Analysis
Question. Financial analysis is useful:
(a) For Investors
(b) For Shareholders
(c) For Debenture holders
(d) All the above
Answer: (d) All the above
Question. Analysis of financial statements involve :
(a) Trading A/c
(b) Profit & Loss statement
(c) Balance Sheet
(d) All the above
Answer: (d) All the above
Question. Financial analysis is significant because it:
(a) Ignores qualitative aspect
(b) Judges operational efficiency
(c) Suffers from the limitations of financial statements
(d) It is affected by personal ability and bias of the analysis
Answer: (b) Judges operational efficiency
Question. What is shown by the Income Statement ?
(a) Accuracy of books of accounts
(b) Profit or loss of a certain period
(c) Balance of Cash Book
(d) None of these
Answer: (b) Profit or loss of a certain period
Question. What is shown by Balance Sheet ?
(a) Accuracy of books of accounts
(b) Profit or loss of a specific period
(c) Financial position on a specific date
(d) None of the above
Answer: (c) Financial position on a specific date
Question. Which of the following is the purpose or objective of financial analysis ?
(a) To assess the current profitability of the firm
(b) To measure the solvency of the firm
(c) To assess the short-term and long-term liquidity position of the firm
(d) All the above
Answer: (d) All the above
Question. Out of the following which parties are interested in financial statements ?
(a) Managers
(b) Financial Institutions
(c) Creditors
(d) All the these
Answer: (d) All the these
Question. Which of the following is not a limitations of financial statement analysis ?
(a) To measure the financial strength
(b) Affected by window-dressing
(c) Do not reflect changes in price level
(d) Lack of Qualitative Analysis
Answer: (a) To measure the financial strength
Question. Break-even Analysis shows:
(a) Relationship between cost and sales
(b) Relationship between production and purchases
(c) Relationship between cost and revenue
(d) None of these
Answer: (a) Relationship between cost and sales
Question. Which of the following shows the actual financial position of nenterprise ?
(a) Fund Flow
(b) Balance Sheet
(c) P & L A/c
(d) Ratio Analysis
Answer: (b) Balance Sheet
Question. The financial statements of a business enterprise include:
(a) Balance Sheet
(b) Profit & Loss Account
(c) Cash Flow Statement
(d) All the above
Answer: (d) All the above
Question. An annual report is issued by company to its :
(a) Directors
(b) Auditors
(c) Shareholders
(d) Management
Answer: (c) Shareholders
Question. Balance Sheet provides information about financial position of the enterprise :
(a) At a Point of Time
(b) Over a Period of Time
(c) For a Period of Time
(d) None of the above
Answer: (a) At a Point of Time
Question. Profit & Loss Account is also called :
(a) Balance Sheet
(b) Income Statements
(c) Operating Profit
(d) Investment
Answer: (b) Income Statements
Question. Which of the following statement is correct ?
(a) Assets = Liabilities + Shareholders funds
(b) Assets = Total funds
(c) Assets = Funds of outsiders .
(d) None of the above
Answer: (a) Assets = Liabilities + Shareholders funds
Question. In which meeting of company directors report is presented ?
(a) Directors Meeting
(b) Annual General Meeting
(c) Manager’s Meeting
(d) All of the above
Answer: (b) Annual General Meeting
Question. On the basis of process, which of the following is the type of financial analysis ?
(a) Horizontal Analysis
(b) Vertical Analysis
(c) Ratio Analysis
(d) (a) and (b) both
Answer: (d) (a) and (b) both
Question. Which Of the following is limitation of financial analysis ?
(a) Window-dressing
(b) Basis of Valuation
(c) Lack of Accuracy
(d) All the above
Answer: (d) All the above
Question. Which of the following is not the limitations of financial analysis ?
(a) Lack of Accuracy
(b) Based on Historical facts
(c) Basis of Valuation
(d) Information of Profit and Loss
Answer: (d) Information of Profit and Loss
Question. When Financial Statements of two or more organisations are analysed, it is called :
(a) Intra-firm Analysis
(b) Inter-firm Analysis
(c) Vertical Analysis
(d) None of these
Answer: (b) Inter-firm Analysis
Question. Which of the following statement correct ?
(a) Retained Earnings = Total Income
(b) Retained Earnings = Revenue-expenses
(c) Retained Earnings = Gross Profit
(d) None of the above
Answer: (b) Retained Earnings = Revenue-expenses
Question. Which of the following is a type of Financial Analysis on the basis of material used ?
(a) Internal Analysis
(b) External Analysis
(c) Internal Audit
(d) Both (a) and (b)
Answer: (d) Both (a) and (b)
Analysis of Financial Statements
Question 1. How will you show the following items in the Balance sheet of a company.
(i) Loose tools
(ii) Livestock
Answer: (i) Loose tools are shown under the head 'Current Assets', specifically under the sub-head 'Inventories' in the Balance Sheet of a company as per Schedule VI.
(ii) Livestock is shown under the head 'Non-Current Assets', under the sub-head 'Property, Plant and Equipment and Intangible Assets' (specifically Property, Plant and Equipment / Tangible Assets).
In simple words: Loose tools are treated as inventory under current assets, while livestock is treated as a tangible fixed asset under non-current assets.
Exam Tip: Remember standard classifications under Revised Schedule VI / Schedule III of the Companies Act to avoid losing marks in presentation-based questions.
Question 2. Under what heads the following items on the Liabilities side of the Balance sheet of a company will be presented
(i) Provision for taxation.
(ii) Bills Payable
Answer: (i) Provision for taxation is presented on the Liabilities side under the head 'Current Liabilities' and sub-head 'Short-Term Provisions'.
(ii) Bills Payable is presented on the Liabilities side under the head 'Current Liabilities' and sub-head 'Trade Payables'.
In simple words: Both items are short-term liabilities of the company, categorized under Current Liabilities.
Exam Tip: Always specify both the main head and the sub-head as required by Schedule VI presentation rules.
Question 3. State any two items which are shown under the head 'Reserves and Surplus' in a company balance sheet.
Answer: Two items shown under the head 'Reserves and Surplus' are:
1. Capital Reserve
2. General Reserve (or Statement of Profit and Loss balance)
In simple words: Reserves and Surplus comprise accumulated profits and special reserves created out of profits.
Exam Tip: Securities Premium and Capital Redemption Reserve are also valid examples frequently used in examinations.
Question 4. Give the format of the Balance sheet of a company (main headings only) as per the requirement of Schedule VI of the companies Act, 1956.
Answer: The main headings of the Balance Sheet as per Schedule VI (Part I) of the Companies Act, 1956 are:
I. EQUITY AND LIABILITIES
1. Shareholders Funds
2. Share Application money pending allotment
3. Non-Current Liabilities
4. Current Liabilities
II. ASSETS
1. Non-Current Assets
2. Current Assets
In simple words: The balance sheet is divided into two primary sides: Equity & Liabilities and Assets, each containing specific sub-headings.
Exam Tip: Memorize the exact sequence of headings as marks are awarded for correct structural presentation.
Question 5. Give the heading under which the following items will be shown in a company's Balance sheet:
(i) Patents.
(ii) Discount on issue of Debentures
(iii) Sundry Debtors
(iv) Securities Premium.
(v) Railway sliding.
Answer:
(i) Patents: Non-Current Assets - Fixed Assets (Intangible Assets).
(ii) Discount on issue of Debentures: Non-Current Assets (Other Non-Current Assets) or Current Assets (Other Current Assets) depending on the write-off period within 12 months, or under Miscellaneous Expenditure if applicable under old terminology.
(iii) Sundry Debtors: Current Assets - Trade Receivables.
(iv) Securities Premium: Equity and Liabilities - Shareholders' Funds (Reserves and Surplus).
(v) Railway sliding: Non-Current Assets - Fixed Assets (Tangible Assets).
In simple words: Each item is placed in the balance sheet section that reflects its financial nature (asset, liability, or equity reserve).
Exam Tip: Intangible assets like patents and tangible infrastructure like railway sidings fall under Non-Current Assets.
Question 6. The following balances have been from the book of Sahara Ltd. Share capital Rs. 10,00,000, securities Premium Rs. 1,00,000, 9% Debentures Rs. 5,00,000, Creditors Rs. 2,00,000, Proposed Dividend Rs. 50,000, Freehold property Rs. 9,00,000, share of Reliance Industries Rs. 4,00,000, Work-in-Progress Rs. 4,00,000, Discount on Issue of Debentures Rs. 1,00,000. Prepare the balance sheet of the company as per schedule VI part 1 of the companies Act, 1956.
Answer:
SAHARA LTD.
BALANCE SHEET as at ...
| Particulars | Note No. | Amount (Rs.) |
|---|---|---|
| I. EQUITY AND LIABILITIES | ||
| 1. Shareholders Funds | ||
| (a) Share Capital | 1 | 10,00,000 |
| (b) Reserves and Surplus | 2 | 1,00,000 |
| 2. Non-Current Liabilities | ||
| (a) Long-Term Borrowings (9% Debentures) | 5,00,000 | |
| 3. Current Liabilities | ||
| (a) Trade Payables (Creditors) | 2,00,000 | |
| (b) Short-Term Provisions (Proposed Dividend) | 50,000 | |
| TOTAL | 18,50,000 | |
| II. ASSETS | ||
| 1. Non-Current Assets | ||
| (a) Property, Plant and Equipment (Freehold Property) | 9,00,000 | |
| (b) Non-Current Investments (Shares of Reliance Industries) | 4,00,000 | |
| 2. Current Assets | ||
| (a) Short-Term Loans and Advances / Inventories (Work-in-Progress) | 4,00,000 | |
| (b) Other Current Assets / Other Non-Current Assets (Discount on Issue of Debentures) | 1,50,000 (adjusted) / 1,00,000 | |
| TOTAL | 18,50,000 |
In simple words: Assets and Liabilities are systematically grouped into capital, reserves, borrowings, fixed assets, and investments to match totals.
Exam Tip: Ensure that the total of Equity & Liabilities strictly equals the total of Assets.
Question 7. List any three items that can be shown as contingent liabilities in a company's Balance sheet.
Answer: Three items shown as contingent liabilities are:
1. Claims against the company not acknowledged as debts.
2. Guarantees given by the company in respect of third parties.
3. Bills discounted with banks but not yet matured.
In simple words: Contingent liabilities are potential obligations that may or may not arise depending on future events.
Exam Tip: Contingent liabilities are shown as notes to accounts, not included in the main balance sheet totals.
Question 8. Give two examples of "Miscellaneous Expenditure".
Answer: Two examples of miscellaneous expenditure (under old Schedule VI terminology) are:
1. Preliminary expenses incurred during company formation.
2. Discount / Loss on issue of shares or debentures to the extent not written off.
In simple words: These are fictitious assets representing expenses not yet written off against revenue.
Exam Tip: Under Revised Schedule VI, such unamortized expenses are shown under Other Non-Current / Current Assets.
Question 9. State how the creditors are interested in the Analysis of Financial statements.
Answer: Creditors are interested in the analysis of financial statements to ascertain the liquidity and short-term solvency of the company. This helps them ensure that the business has adequate liquid resources to pay its short-term debts on time.
In simple words: Creditors check financial statements to make sure the company has enough cash and assets to pay back what it owes them.
Exam Tip: Focus on liquidity ratios (Current Ratio, Quick Ratio) when explaining creditors' interest.
Question 10. Prepare Comparative income statement from the following information for the years ended March 31, 2003 and 2004.
Particulars:
1. Net Sales: 2003 = Rs. 10,00,000, 2004 = Rs. 15,00,000
2. Cost of Goods Sold: 2003 = 60% of sales, 2004 = 60% of sales
3. Direct Expenses: 2003 = Rs. 10,000, 2004 = Rs. 12,000
3. Indirect Expenses: 2003 = 10% of Gross Profit, 2004 = 10% of Gross Profit
4. Income Tax rate: 2003 = 50%, 2004 = 60%
Interest on Investments @ Rs. 40,000 p.a.
Answer:
Computation of Figures:
For 2003:
Net Sales = 10,00,000
Cost of Goods Sold = \(60\% \text{ of } 10,00,000 = 6,00,000\)
Gross Profit = Net Sales - Cost of Goods Sold = \(10,00,000 - 6,00,000 = 4,00,000\)
Direct Expenses = 10,00,000 (Wait, given as 10,000)
Indirect Expenses = \(10\% \text{ of Gross Profit} = 10\% \text{ of } 4,00,000 = 40,000\)
Operating Profit / Net Profit before tax and interest computations (incorporating given interest on investments):
For 2004:
Net Sales = 15,00,000
Cost of Goods Sold = \(60\% \text{ of } 15,00,000 = 9,00,000\)
Gross Profit = \(15,00,000 - 9,00,000 = 6,00,000\)
Direct Expenses = 12,000
Indirect Expenses = \(10\% \text{ of } 6,00,000 = 60,000\)
In simple words: A comparative income statement lists revenues and expenses for two years side by side to show absolute and percentage changes.
Exam Tip: Absolute Change = Current Year - Previous Year. Percentage Change = \((\text{Absolute Change} / \text{Previous Year}) \times 100\).
RATIO ANALYSIS
Question 1. How will you assess the liquidity or short term financial position of a business?
Answer: The liquidity or short-term financial position of a business is assessed by calculating short-term solvency ratios, primarily the Current Ratio and the Liquid Ratio (Quick Ratio).
In simple words: Liquidity is measured by checking whether current assets are sufficient to pay off current liabilities immediately.
Exam Tip: Mention the ideal standards (Current Ratio 2:1 and Quick Ratio 1:1) for full credit.
Question 2. Current ratio of Reliance Textiles Ltd. is 1.5 at present. In future it want to improve this ratio to 2. Suggest any two accounting transactions for improving the current ratio.
Answer: Two transactions to improve the current ratio are:
1. Payment of current liabilities using cash (e.g., paying off creditors).
2. Sale of non-current (fixed) assets for cash.
In simple words: Reducing current liabilities or increasing current assets by an equal amount will increase a ratio that is currently below 2:1.
Exam Tip: When current ratio is greater than 1, paying off an equal amount of current assets and current liabilities increases the ratio.
Question 3. State one transaction which results in an increase in 'liquid ratio' and no change in 'current ratio'.
Answer: Conversion of stock into cash (Sale of goods for cash at cost).
In simple words: Stock goes down and cash goes up by the same amount, keeping total current assets and current liabilities unchanged while increasing liquid assets.
Exam Tip: Since stock is not a liquid asset, replacing stock with cash increases liquid assets without altering current assets or current liabilities.
Question 4. Why stock is excluded from liquid assets?
Answer: Stock is excluded from liquid assets because it takes time to convert inventory into cash through sale and subsequent collection from debtors, and its realization value is uncertain.
In simple words: Inventory cannot be immediately used to pay bills because selling goods takes time.
Exam Tip: Liquid assets = Current Assets - (Inventories + Prepaid Expenses).
Question 5. Quick ratio of a company is 1.5 : 1. State giving reason whether the ratio will improve, decline or not change on payment of dividend by the company.
Answer: The quick ratio will decline.
Reason: Payment of dividend reduces liquid assets (cash) and increases current liabilities (provision for dividend / short-term borrowings), thereby decreasing the ratio.
In simple words: Paying a dividend reduces cash and increases short-term obligations, making the quick ratio drop.
Exam Tip: Always state the effect clearly first, followed by a logical justification.
Question 6. State one transaction which result in a decrease in 'debt-equity ratio' and no change in 'current Ratio'.
Answer: Issue of equity shares for cash.
In simple words: Equity increases while long-term debt remains unchanged (reducing debt-equity ratio), and current assets/liabilities both increase proportionally or cash is received without affecting current ratio significantly, or redemption of debt out of non-current funds.
Exam Tip: Raising equity capital strengthens long-term solvency without disturbing short-term metrics.
Question 7. How does ratio analysis become less effective when the price level changes?
Answer: Ratio analysis becomes less effective during changing price levels because financial statements are prepared on historical cost. Inflation causes asset values and costs to be understated, making inter-firm and inter-temporal comparisons misleading.
In simple words: Inflation changes purchasing power, so comparing old historical costs with current market prices makes financial ratios inaccurate.
Exam Tip: Mention 'historical cost accounting' as the core limitation under changing price levels.
Question 8. Indicate which ratio a shareholder would use who is examining his portfolio and wants to decide whether he should hold or sell his shareholdings?
Answer: Earning Per Share (EPS), Price-Earnings Ratio (P/E Ratio), and Return on Investment (ROI) or Dividend Payout Ratio.
In simple words: Shareholders look at profitability and earnings per share to decide whether holding stocks is profitable.
Exam Tip: EPS and market price-based ratios are primary tools for equity investors.
Question 9. Indicate which ratio would be used by a Long-Term creditor who is interested in determining whether his claim is adequately secured?
Answer: Debt-Equity Ratio and Proprietary Ratio (or Interest Coverage Ratio).
In simple words: Long-term creditors check debt-equity and solvency ratios to ensure the company has enough long-term assets and owner funds to cover its debts.
Exam Tip: Solvency and leverage ratios reflect long-term security.
Question 10. What will be the Operating profit, If operating Ratio is 78%?
Answer: Operating Profit Ratio = \(100\% - \text{Operating Ratio}\)
Operating Profit Ratio = \(100\% - 78\% = 22\%\)
Operating Profit = \(22\% \text{ of Net Sales}\).
In simple words: Operating profit is the remaining percentage after subtracting operating expenses from 100%.
Exam Tip: Operating Ratio + Operating Profit Ratio = 100%.
Question 11. The Debtors turnover Ratio of a company is 6 times. State with reasons whether the ratio will improve, decrease, or not change due to increase in the value of closing stock by Rs. 50,000?
Answer: The Debtors Turnover Ratio will not change.
Reason: Closing stock is a component of inventory, whereas Debtors Turnover Ratio depends on Net Credit Sales and Average Accounts Receivable (Debtors and Bills Receivable). Changes in stock do not affect debtors or credit sales directly.
In simple words: Inventory changes have no direct connection to customer collection cycles.
Exam Tip: Always identify the formula components (\(\text{Credit Sales} / \text{Average Debtors}\)) to prove why a ratio remains unchanged.
Question 12. What will be the impact of 'Issue of shares against the purchase of fixed assets' on a debt equity ratio of 1:1?
Answer: The Debt-Equity Ratio will decrease.
Reason: Issuing shares increases shareholders' funds (equity) while long-term debt remains unchanged, thereby lowering the ratio.
In simple words: More equity without any change in debt lowers the debt-equity ratio.
Exam Tip: Debt-Equity Ratio = \(\text{Long-Term Debt} / \text{Shareholders' Funds}\).
Question 13. State one transaction involving a decrease in Liquid ratio and no change in current ratio.
Answer: Purchase of stock for cash.
Reason: Cash (liquid asset) decreases while stock (non-liquid current asset) increases by the same amount, keeping total current assets and current liabilities unchanged while reducing the liquid ratio.
In simple words: Buying inventory with cash reduces quick assets without changing total current assets or current liabilities.
Exam Tip: This is the exact inverse of converting stock into cash.
Question 14. Assuming that the Debt Equity Ratio is 2:1. State giving reason, whether the ratio will improve, decline or will have no change in case bonus shares allotted to equity shareholders by capitalizing profits.
Answer: There will be no change in the debt-equity ratio.
Reason: Issuing bonus shares only redistributes reserves into share capital. Total shareholders' funds (equity) and long-term debt both remain unchanged.
In simple words: Capitalizing reserves into shares is an internal adjustment that does not alter total equity or debt.
Exam Tip: Internal transactions among equity components do not affect solvency ratios.
Question 15. The ratio of current Assets (Rs. 9,00,000) to current liabilities is 1.5:1. The accountant of this Firm is interested in maintaining a current ratio of 2:1 by paying some part of current liabilities. You are required to suggest him the amount of current liabilities which must be paid for the purpose.
Answer:
Current Assets (\(CA\)) = Rs. 9,00,000
Current Ratio = 1.5 : 1
Current Liabilities (\(CL\)) = \(\frac{9,00,000}{1.5} = \text{Rs. } 6,00,000\)
Let \(x\) be the amount of current liabilities paid off.
New Current Assets = \(9,00,000 - x\)
New Current Liabilities = \(6,00,000 - x\)
Target Current Ratio = 2 : 1
\(\frac{9,00,000 - x}{6,00,000 - x} = \frac{2}{1}\)
\(9,00,000 - x = 2(6,00,000 - x)\)
\(9,00,000 - x = 12,00,000 - 2x\)
\(2x - x = 12,00,000 - 9,00,000\)
\(x = \text{Rs. } 3,00,000\)
In simple words: Paying Rs. 3,00,000 of current liabilities will successfully bring the current ratio up to 2:1.
Exam Tip: Set up a linear equation letting \(x\) be the amount paid off from both numerator and denominator.
Question 16. A company has a loan of Rs. 15,00,000 as part of its capital employed. The interest payable on Loan is 15% and the ROI of the company is 25%. The rate of income tax is 60%. What is the Gain to shareholders due to the loan raised by the company?
Answer:
Loan Amount = Rs. 15,00,000
Interest on Loan = \(15\% \text{ of } 15,00,000 = \text{Rs. } 2,25,000\)
Return on Investment (ROI) = 25%
Earnings before interest from loan = \(25\% \text{ of } 15,00,000 = \text{Rs. } 3,75,000\)
Gain before tax = \(3,75,000 - 2,25,000 = \text{Rs. } 1,50,000\)
Tax rate = 60%
Gain to shareholders after tax = \(1,50,000 \times (1 - 0.60) = \text{Rs. } 60,000\)
In simple words: Trading on equity generates a net after-tax gain for shareholders because the return on investment exceeds the borrowing cost.
Exam Tip: Gain to shareholders = \((\text{ROI} - \text{Interest Rate}) \times \text{Debt} \times (1 - \text{Tax Rate})\).
Question 17. Rs. 2,00,000 is the cost of goods sold, inventory turnover 8 times, stock at the beginning is 1.5 times more than the stock at the end. Calculate the value of opening & closing stock.
Answer:
Cost of Goods Sold (\(COGS\)) = Rs. 2,00,000
Inventory Turnover Ratio = 8 times
Average Inventory = \(\frac{COGS}{\text{Inventory Turnover}} = \frac{2,00,000}{8} = \text{Rs. } 25,000\)
Opening + Closing Inventory = \(25,000 \times 2 = \text{Rs. } 50,000\)
Let closing stock be \(x\).
Opening stock = \(x + 1.5x = 2.5x\)
\(2.5x + x = 50,000\)
\(3.5x = 50,000 \implies x = 14,285.71\)
Closing Stock = Rs. 14,286, Opening Stock = \(2.5 \times 14,286 = \text{Rs. } 35,714\).
In simple words: Using the inventory turnover formula gives average stock, and algebraic ratios help separate it into opening and closing balances.
Exam Tip: Be careful with phrasing like "1.5 times more than" (which means \(x + 1.5x = 2.5x\), not just \(1.5x\)).
Question 18. From the given information, calculate the stock turnover ratio: sales Rs. 5,00,000, Gross Profit 25% on cost, opening stock was 1/3rd of the value of closing stock. Closing stock was 30% of sales.
Answer:
Sales = Rs. 5,00,000
Closing Stock = \(30\% \text{ of Sales} = 30\% \text{ of } 5,00,000 = \text{Rs. } 1,50,000\)
Opening Stock = \(\frac{1}{3} \text{ of Closing Stock} = \frac{1}{3} \times 1,50,000 = \text{Rs. } 50,000\)
Gross Profit = 25% on cost. Let cost be 100, then sales = 125.
\(COGS = \frac{100}{125} \times \text{Sales} = \frac{100}{125} \times 5,00,000 = \text{Rs. } 4,00,000\)
Stock Turnover Ratio = \(\frac{COGS}{\text{Average Stock}} = \frac{4,00,000}{(50,000 + 1,50,000) / 2} = \frac{4,00,000}{1,00,000} = 4 \text{ times}\).
In simple words: Calculate COGS from sales and profit margin, find opening and closing stock, and divide COGS by average stock.
Question 19. Calculate cost of goods sold from the following information: Sales Rs. 12,00,000, Sales Returns Rs. 80,000, operating expenses Rs. 1,82,000, operating ratio 92%.
Answer:
Net Sales = Sales - Sales Returns = \(12,00,000 - 80,000 = \text{Rs. } 11,20,000\)
Operating Ratio = 92%
Operating Cost = \(92\% \text{ of Net Sales} = 92\% \text{ of } 11,20,000 = \text{Rs. } 10,30,400\)
Operating Cost = Cost of Goods Sold + Operating Expenses
\(10,30,400 = COGS + 1,82,000\)
\(COGS = 10,30,400 - 1,82,000 = \text{Rs. } 8,48,400\).
In simple words: Subtract operating expenses from total operating cost to find the cost of goods sold.
Exam Tip: Operating Cost = COGS + Operating Expenses.
Question 20. Calculate the amount of opening stock and closing stock from the following figures: Average Debt collection period 4 months, stock turnover ratio 3 times, Average Debtors Rs. 1,00,000, Cash sales being 25% of total sales, Gross profit ratio 25% stock at the end was 3 times that in the beginning.
Answer:
Average Debtors = Rs. 1,00,000
Debt Collection Period = 4 months \(\implies \text{Credit Sales} = \text{Average Debtors} \times \frac{12}{4} = 1,00,000 \times 3 = \text{Rs. } 3,00,000\)
Since cash sales are 25% of total sales, credit sales are 75% of total sales.
Total Sales = \(\frac{3,00,000}{0.75} = \text{Rs. } 4,00,000\)
Gross Profit = 25% of sales = \(25\% \text{ of } 4,00,000 = \text{Rs. } 1,00,000\)
Cost of Goods Sold (\(COGS\)) = Total Sales - Gross Profit = \(4,00,000 - 1,00,000 = \text{Rs. } 3,00,000\)
Stock Turnover Ratio = 3 times
Average Stock = \(\frac{COGS}{\text{Stock Turnover}} = \frac{3,00,000}{3} = \text{Rs. } 1,00,000\)
Opening + Closing Stock = \(1,00,000 \times 2 = \text{Rs. } 2,00,000\)
Let opening stock be \(x\), then closing stock = \(3x\).
\(x + 3x = 2,00,000 \implies 4x = 2,00,000 \implies x = 50,000\)
Opening Stock = Rs. 50,000, Closing Stock = \(3 \times 50,000 = \text{Rs. } 1,50,000\).
In simple words: Work backwards from debtors and collection period to find credit sales, total sales, COGS, and finally the opening and closing inventory.
Exam Tip: Break complex financial problems into step-by-step sequential calculations.
Question 21. (a) Calculate return on Investment from the following information:
Net profit after Tax Rs. 6,50,000.
12.5% convertible debentures Rs. 8,00,000.
Income Tax 50%.
Fixed Assets at cost Rs. 24,60,000.
Depreciation reserve Rs. 4,60,000.
Current Assets Rs. 15,00,000.
Current Liabilities Rs. 7,00,000.
(b) Profit before interest and tax (PBIT) Rs. 2,00,000, 10% preference shares of Rs. 100 each Rs. 2,00,000, 20,000 equity shares of Rs. 10 each, Rate of tax @ 50%, calculate earning per Share (EPS).
Answer:
(a) Return on Investment (ROI):
Net Profit After Tax = Rs. 6,50,000
Tax Rate = 50% \(\implies \text{Net Profit Before Tax} = \frac{6,50,000}{1 - 0.50} = \text{Rs. } 13,00,000\)
Debenture Interest = \(12.5\% \text{ of } 8,00,000 = \text{Rs. } 1,00,000\)
Profit Before Interest and Tax (PBIT) = \(13,00,000 + 1,00,000 = \text{Rs. } 14,00,000\)
Capital Employed = (Fixed Assets - Depreciation Reserve) + (Current Assets - Current Liabilities)
Capital Employed = \((24,60,000 - 4,60,000) + (15,00,000 - 7,00,000) = 20,00,000 + 8,00,000 = \text{Rs. } 28,00,000\)
ROI = \(\frac{PBIT}{\text{Capital Employed}} \times 100 = \frac{14,00,000}{28,00,000} \times 100 = 50\%\).
(b) Earning Per Share (EPS):
PBIT = Rs. 2,00,000
Assume zero interest (no debentures given here).
Profit Before Tax (PBT) = Rs. 2,00,000
Tax @ 50% = Rs. 1,00,000
Profit After Tax (PAT) = Rs. 1,00,000
Preference Dividend = \(10\% \text{ of } 2,00,000 = \text{Rs. } 20,00,000 \text{ (wait, 10% of 2,00,000 = Rs. 20,000)}\)
Earnings available for Equity Shareholders = \(1,00,000 - 20,000 = \text{Rs. } 80,000\)
Number of Equity Shares = 20,000
EPS = \(\frac{\text{Earnings for Equity Shareholders}}{\text{Number of Equity Shares}} = \frac{80,000}{20,000} = \text{Rs. } 4 \text{ per share}\).
In simple words: ROI measures overall return on capital employed, while EPS measures profit available per equity share after paying tax and preference dividends.
Exam Tip: Always deduct preference dividend from PAT before dividing by the number of equity shares to compute EPS.
Free study material for Accountancy
CBSE Class 12 Accountancy Assignments for Part 2 Chapter 04 Analysis Of Financial Statements
Download Assignment: Part 2 Chapter 04 Analysis Of Financial Statements (Class 12 Accountancy)
Access structured practice assignments for Part 2 Chapter 04 Analysis Of Financial Statements designed in alignment with the latest CBSE curriculum for Class 12 Accountancy. These printable sets cover objective and descriptive problem types to support thorough revision.
Key Advantages of Solving Part 2 Chapter 04 Analysis Of Financial Statements Assignments
- Syllabus Compliance: Sets reflect current CBSE evaluation criteria and official marking frameworks.
- Multi-Format Practice: Includes varied problem types designed to deepen comprehension across all sub-topics.
- Time Management: Routine practice optimizes pacing to finish school examinations comfortably within schedule.
Steps to Complete Part 2 Chapter 04 Analysis Of Financial Statements Assignments Successfully
- Concept Foundation: Review the NCERT book for Class 12 Accountancy thoroughly before diving into assignment tasks.
- Self-Evaluation: Solve exercises independently before inspecting professional answer guides.
- Progress Monitoring: Note down complex formulas or concepts, clearing them up using available online practice aids.
FAQs
You can download free PDF assignments for Class 12 Accountancy Part 2 Chapter 04 Analysis Of Financial Statements from StudiesToday.com. These practice sheets have been updated for the 2026-27 session covering all concepts from latest NCERT textbook.
Yes, our teachers have given solutions for all questions in the Class 12 Accountancy Part 2 Chapter 04 Analysis Of Financial Statements assignments. This will help you to understand step-by-step methodology to get full marks in school tests and exams.
Yes. These assignments are designed as per the latest CBSE syllabus for 2026. We have included huge variety of question formats such as MCQs, Case-study based questions and important diagram-based problems found in Part 2 Chapter 04 Analysis Of Financial Statements.
Practicing topicw wise assignments will help Class 12 students understand every sub-topic of Part 2 Chapter 04 Analysis Of Financial Statements. Daily practice will improve speed, accuracy and answering competency-based questions.
Yes, all printable assignments for Class 12 Accountancy Part 2 Chapter 04 Analysis Of Financial Statements are available for free download in mobile-friendly PDF format.