

Accountancy Concept Notes for Class 11: Chapter 11 Accounts from Incomplete Records
Review targeted revision notes for Class 11 Accountancy with the CBSE Class 11 Accountancy Accounts For Incomplete Records Notes Set 02. Built according to official educational guidelines for the 2026-27 academic year, these downloadable summaries for Chapter 11 Accounts from Incomplete Records support daily study and last-minute exam readiness.
Download Chapter 11 Accounts from Incomplete Records Revision Notes PDF
Navigate directly to the revision notes for Chapter 11 Accounts from Incomplete Records using the digital viewer below. Each summary is structured to highlight high-weightage sections, allowing students to instantly access critical definitions and focus on core exam topics.
UNIT:10
ACCOUNTS FOR INCOMPLETE RECORDS
“A system of book-keeping in which, as a rule, only records of cash and of personal accounts are maintained, it is always incomplete double entry system, varying with circumstances” Unit at a Glance:
- Introduction
- Salient features
- Uses
- Limitations
- Difference between double entry system and incomplete records
- Ascertainment of profit or loss from incomplete records
- Conversion into double entry method
- numerical exercises
Introduction:
Accounting records which are not prepared in accordance with double entry system method are described as accounts for incomplete records. SALIENT FEATURES
1. Apply of personal accounts only ( ignores nominal and real accounts)
2. Maintenance of cash book.( Cash book is prepared )
3. Based on original vouchers. (Collection of data is made with original vouchers)
4. Lack of Similarity. (Method of preparation of books differs from firm to firm, it prepared as per the need of the business.
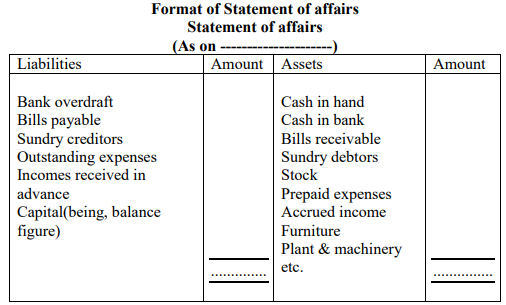
5. Preparation of final accounts. (After converting the information into double entry system final accounts are prepared. Due to this Statement of affairs is prepared instead of Balance sheet)
Uses
1. Easy method (Not requires any specific knowledge)
2. Economical( Can be prepared by without having more staff)
3. Suitable for small concerns (Few assets and liabilities are to be recorded)
4. Not – rigid (Can be modified/changed as per requirement of business)
5. Easy finding of profit & losses. (Only opening and Closing capital is required)
Limitations
1. Impossible to find fraud (As Trial balance is ignored)
2. Incomplete system (No set rules are followed)
3. Unable to find adequate profit & losses. (Ignorance of nominal accounts)
4. Difficulty in preparation of balance sheet.(Lack of valuation of goodwill)
5. Unable to retain full control on asserts. (Real accounts are ignored, it is difficult to make full control on assets)
6. Unsuitable for planning in control(Lack of reliable figure)
7. Lack of internal checking(Fails to adopt double entry system)
8. Improper evaluation of asserts (Ignorance of certain information like depreciation etc.)
DIFFERENCE BETWEEN DOUBLE ENTRY SYSTEM & INCOMPLETE RECORDS
Basis of difference Recording of both aspects (Double entry records every transaction and incomplete records few transactions)
1. Type of accounts (All accounts are considered in double entry only personal account are considered in incomplete records)
2. Trial balance (Trial balance is prepared in double entry system,Trial balance is not prepared in incomplete records )
3. Net profit/ loss (Profit/Loss is calculated by preparing trading and profit &loss a/c in double entry system, Statement of profit is prepared in incomplete records to find the same.
4. Financial position (Balance sheet is prepared in double entry and statement of affairs is prepared in incomplete records)
5. Adjustment (Adjustment are considered in double entry ,while adjustments are not considered in incomplete records)
ASCERTAINMENT OF PROFIT OR LOSS FROM INCOMPLETE RECORDS
1. Statements of affairs method
2. Conversion into double entry method
Statement of affairs method: Under this method Opening and Closing capital is calculated. Then statement of profit is prepared to find profit/loss during the year.


Please click the link below to download pdf file for CBSE Class 11 Accountancy Accounts For Incomplete Records Notes Set B.
Free study material for Accountancy
Revision Notes and Key Concepts for Class 11 Accountancy Chapter 11 Accounts from Incomplete Records
About Chapter 11 Accounts from Incomplete Records Revision Notes
Review targeted chapter notes for Class 11 Accountancy Chapter 11 Accounts from Incomplete Records. Built according to official CBSE guidelines, these summaries highlight high-yield topics frequently tested in school evaluations.
How to Use These Revision Notes
Built using the official NCERT book for Class 11 Accountancy, these notes provide reliable academic guidance. Pair your summary review with our recommended NCERT solutions to master optimal problem-solving approaches.
Enhance Practice with MCQs and Worksheets
Follow up your revision by attempting the interactive online Accountancy MCQ test and practice worksheets for this chapter to verify your mastery. All platform resources are free to access.
FAQs
You can download the teacher prepared revision notes for CBSE Class 11 Accountancy Accounts For Incomplete Records Notes Set 02 from StudiesToday.com. These notes are designed as per 2026-27 academic session to help Class 11 students get the best study material for Accountancy.
Yes, our CBSE Class 11 Accountancy Accounts For Incomplete Records Notes Set 02 include 50% competency-based questions with focus on core logic, keyword definitions, and the practical application of Accountancy principles which is important for getting more marks in 2026 CBSE exams.
Yes, our CBSE Class 11 Accountancy Accounts For Incomplete Records Notes Set 02 provide a detailed, topic wise breakdown of the chapter. Fundamental definitions, complex numerical formulas and all topics of CBSE syllabus in Class 11 is covered.
These notes for Accountancy are organized into bullet points and easy-to-read charts. By using CBSE Class 11 Accountancy Accounts For Incomplete Records Notes Set 02, Class 11 students fast revise formulas, key definitions before the exams.
No, all study resources on StudiesToday, including CBSE Class 11 Accountancy Accounts For Incomplete Records Notes Set 02, are available for immediate free download. Class 11 Accountancy study material is available in PDF and can be downloaded on mobile.