

Official Class 12 Accountancy Revision Material: CBSE Class 12 Accountancy Goodwill Nature And Valuation Notes
Access comprehensive revision notes for Part 1 Chapter 01 Accounting for Partnership Basic Concepts using the CBSE Class 12 Accountancy Goodwill Nature And Valuation Notes. Designed to align with the 2026-27 academic syllabus for Class 12 Accountancy, these concept summaries help students streamline their exam preparation and review complex topics efficiently.
Chapter-wise Concept Summaries: Part 1 Chapter 01 Accounting for Partnership Basic Concepts
View or download the dedicated Part 1 Chapter 01 Accounting for Partnership Basic Concepts revision resource below. Engaging with these structured concept notes daily ensures continuous academic progress and mastery of the 2026-27 curriculum for Accountancy.
CHAPTER 2
Goodwill : Nature and Valuation
Meaning of Goodwill:
Goodwill places the organization at a good position due to which the organization is able to earn higher profits without any extra efforts. Goodwill cannot be seen but felt. Therefore goodwill is called an Intangible asset.
Factors affecting the value of Goodwill :
1. Efficient management
2. Quality of products
3. Location of business
4. Availability of raw material
5. Favorable contracts
Need for valuing goodwill : Whenever the mutual rights of the partners changes then party which makes a sacrifice must be compensated. This basis of compensation is goodwill so we need to calculate goodwill. Mutual rights change under following circumstances
1) When profit sharing ratio changes
2) On admission of a partner
3) On Retirement or death of a partner
4) When amalganation of two firms taken place.
5) When partnership firm is sold.
Methods of valuation of goodwill :
1. Average profit method
2. Super profit method
3. Capitalization method
Average Profit Method
The profit earned by a Firm during previous accounting periods on an average basis is called average profit. Goodwill is calculated on the basis of average profit due to future expectations of earning capacity of the firm.
Illustration 1. (Average Profit Method)
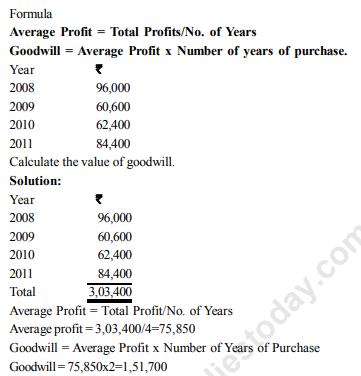
Akanksha,Chetna and Dipanshu are partners in a firm sharing profits and losses in the ratio of 3:2:1. They decide to take Jatin into partnership from January 1,2012 for 1/5 share in the future profits. For this purpose , goodwill is to be valued at 2 times the average annual profits of the previous four years. The average profits for the past four years were:
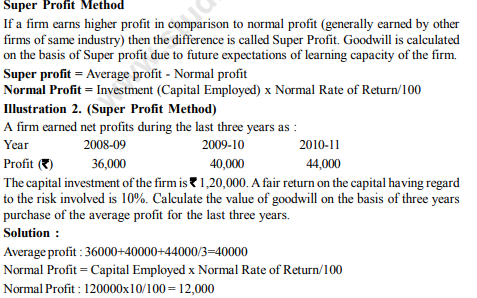
Super profit = Average profit Normal profit
= 40,00012,000=28,000
Goodwill = Super profit x number of years purchased
= 28,000 x 3 = 84,000
Capitalisation Method
In this method capitalized value of the firm is calculated on the basis of normal rate of return. Difference between teh capitalized value and actual capital employed is called goodwill.
Illustration 3 (Capitalisation Method)
A earns ` 1,20,000 as its annual profits, the rates of normal profit being 10% The assets of teh firm amounted to ` 14,40,000 and liabilities to ` 4,80,000. Find out the value of goodwill by capitalization method.
Solution :
Capitalized value of the firm = Average profit x 1000/ Rate of normal profit
= 1,20,000x10/100 = 12,00,0005
Capital employed = Total assets liabilities
= 14,40,000 4,80,000 = 9,60,000
Goodwill = capitalized value capital employeed
= 12,00,0009,60,000=2,40,000
Illustration 4 . (Average profit method)
A and B are partners in a firm. They admit C into the firm. The goodwill for the purpose is to be calculated at 2 year's purchase of the average normal profits of the last three years which were ` 10,000, ` 15,000 and ` 30,000 respectively. Second years profit included profit on sale of Machinery ` 10,000. Find the value of goodwill of the firm on C's Admission.
Solution
(1) Calculation of Average Profit :
Year ended `
Ist Year 10,000
2nd Year (`15,000`10,000) 5,000
3rd Year 30,000
Total Profits 45,000
Average profit = Total profit/No. of years
= ` 45,000/3=15,000
Illustration 5 (Super profit method)
The average net profits expected of a firm in future are ` 68,000 per year and capita invested in the business by the firm is ` 3,50,000. The rate of interest expected from capital invested in this class of business is 12%. The remuneration of the partners is estimated to be ` 8,000 for the year. You are required to find out the value of goodwill on the basis of two years' purchase of super profits.
Solution
Average Profit = Average Net Profit Partner's remuneration
(1) Average profit = ` 68,000` 8,000 = `60,000
(ii) Normal profit= Capital employed x Normal rate of return/100
= ` 3,50,000x12/100= ` 42,000
(iii) Super Profit = Average profit Normal profit
= ` 60,000 ` 42,000 = ` 18,000
(iv) Value of goodwill = Super profit x No. of years ' purchase
= ` 18,000x2 = ` 36,000
Illustration 6. (Super profit method)
On April 1st, 1998 an existing firm had assets of ` 75,000 including cash of ` 5,000. The partners' capital accounts showed a balance of ` 60,000 and reserves constituted the rest. If the normal rate of return is 20% and the goodwill of the firm is valued at ` 24,000 at 4 years purchase of super profits, find the averages profits of the firm
Solution :
(1) Calculation of Normal Profit : Capital employed x normal rate/100 =75,000x20/100 = ` 15,000
(2) Calculation of Super Profit :
Goodwill = Super profit x No. of years' purchase
` 24,000 = Super Profit x4
Super Profit = ` 24,000 = `6,000
(3) Calculating of Average Profit :
Super Profit = Average Profit Normal Profit
` 6,000 = Average Profit ` 15,000
Average Profit = ` 6,000+ ` 15,000 = ` 21,000
Please click the link below to download pdf file for CBSE Class 12 Goodwill-Nature and Valuation.
Free study material for Accountancy
Revision Notes and Key Concepts for Class 12 Accountancy Part 1 Chapter 01 Accounting for Partnership Basic Concepts
Key Concepts and Summary for Class 12 Accountancy Part 1 Chapter 01 Accounting for Partnership Basic Concepts
Review targeted chapter notes for Class 12 Accountancy Part 1 Chapter 01 Accounting for Partnership Basic Concepts. Built according to official CBSE guidelines, these summaries highlight high-yield topics frequently tested in school evaluations.
NCERT-Aligned Chapter Summary and Notes
Each chapter summary is structured around standard CBSE textbooks, allowing students to check their understanding and clarify complex ideas early in their revision.
Next Steps in Your Exam Preparation
Wrap up your chapter revision by testing your knowledge against standard question formats. Everything on our platform is provided free of charge.
FAQs
You can download the teacher prepared revision notes for CBSE Class 12 Accountancy Goodwill Nature And Valuation Notes from StudiesToday.com. These notes are designed as per 2026-27 academic session to help Class 12 students get the best study material for Accountancy.
Yes, our CBSE Class 12 Accountancy Goodwill Nature And Valuation Notes include 50% competency-based questions with focus on core logic, keyword definitions, and the practical application of Accountancy principles which is important for getting more marks in 2026 CBSE exams.
Yes, our CBSE Class 12 Accountancy Goodwill Nature And Valuation Notes provide a detailed, topic wise breakdown of the chapter. Fundamental definitions, complex numerical formulas and all topics of CBSE syllabus in Class 12 is covered.
These notes for Accountancy are organized into bullet points and easy-to-read charts. By using CBSE Class 12 Accountancy Goodwill Nature And Valuation Notes, Class 12 students fast revise formulas, key definitions before the exams.
No, all study resources on StudiesToday, including CBSE Class 12 Accountancy Goodwill Nature And Valuation Notes, are available for immediate free download. Class 12 Accountancy study material is available in PDF and can be downloaded on mobile.